How proposed changes to Canada’s dividend rules could affect certain tax refunds
Proposed changes to Canada’s dividend rules could determine whether related tax refunds are delayed—or potentially lost—for corporate groups with mismatched year-ends.
When a private business is carried on through a corporate structure with holding companies, subsidiaries or trusts, it is common for money to move between those entities in the form of dividends. Canada's tax system generally allows a corporation to recover certain taxes when it pays a dividend so that those same amounts are not taxed multiple times as they move through these entities.
The federal government proposed new rules that could delay access to those tax refunds when a dividend is paid to a related corporation whose taxation year ends after that of the corporation paying the dividend. These dividends would be known as suspended dividends.
As Parliament considers these changes, Canadian corporate groups that could be affected should pay careful attention to two key practical concerns:
-
Tracking: Corporate groups with complex structures would need robust processes to track suspended dividends and related refund balances across entities and taxation years. Without adequate record-keeping, these organizations may face challenges identifying when conditions to release the dividend refund are satisfied, which may potentially delay or forfeit access to available dividend refunds.\
-
Unrecoverable dividends: The proposed rules are intended to defer dividend refunds until dividends are paid outside the affiliated group. However, a refund may never be realized under certain circumstances—including if there are insufficient funds preventing a dividend from being distributed outside the corporate group or an acquisition of control occurs outside specified timelines. In those instances, the refund on the suspended dividend may remain trapped indefinitely, which would result in permanent double-taxation. Taxpayers should consult with appropriate advisors to ensure dividend release conditions will be met.
How the Part IV tax system works
The recovery of certain taxes when dividends are paid between entities is accomplished through the Part IV tax system.
It implements the tax principle of integration— which says that income earned through a corporation and later distributed to an individual should generally bear approximately the same overall tax as if the income had been earned directly by the individual.
Part IV tax is paid on taxable dividends received by a corporation to the extent the dividend is deductible from the recipient’s income. This rule applies when the corporation receiving the dividend is a private corporation or certain closely held public corporations resident in Canada.
The tax is payable with the corporation’s year-end tax liability, but is refundable when taxable dividends are subsequently paid to shareholders.
If dividends move through several corporations before being paid to ultimate shareholders, Part IV tax effectively follows the dividends through the corporate chain. The tax is paid when a corporation receives the dividend and is generally refunded when that corporation pays taxable dividends onward.
The tax will ultimately be paid by the individual shareholder upon receipt of the dividend.
The mismatched year-end problem
For corporations with the same year-end, the refund and Part IV tax will be remitted in the same year.
But for entities with mismatched year-ends, the refund and Part IV tax can be payable in different years—as illustrated below.
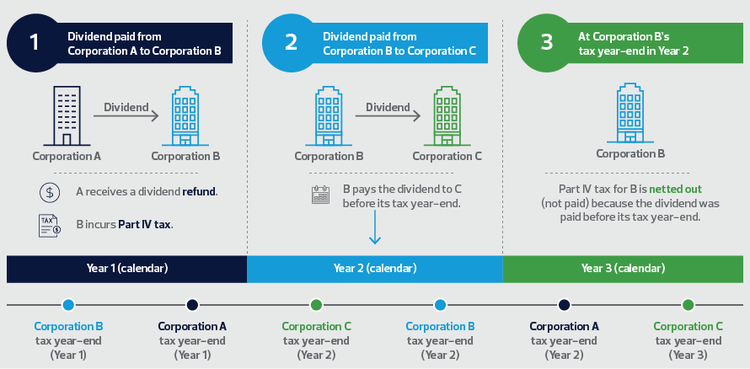
Sources: DLA Piper; RSM Canada
As outlined, the first payor corporation receives a dividend refund in Year One. In that example, Year Three is the earliest point where Part IV tax may be remitted to the Canada Revenue Agency (CRA).
If this trend continues with further corporations in the corporate chain, the payment of Part IV tax or tax payable by the individual shareholders could be further delayed.
The newly proposed rules are intended to prevent this multi-year deferral.
Understanding the proposed changes
Under the proposed rules, no dividend refund will be issued on suspended dividends.
A dividend is considered suspended when it is paid to an affiliated private corporation and the recipient corporation's taxation year ends after the payor corporation's taxation year in which the dividend was paid.
This suspension rule does not apply if:
- Dividends with the same eligible or ineligible character as the dividend being paid were already distributed outside the affiliated group. The dividend amount must be within a specified amount of the payor’s expected dividend refund.
- A loss restriction event, such as an acquisition of control, occurs within 30 days of the dividend payment—or within 12 months if the dividend was paid in contemplation of the event.
Suspended dividends can also be released—meaning the refund will be paid—if the following conditions are all met:
- Dividends with the same eligible or ineligible character as the dividend being paid were paid outside the affiliated and connected corporate group in an amount at least equal to the suspended amount.
- No loss-restriction event occurred while the dividend was suspended.
- The dividend used to satisfy this test was not used by another corporation to receive a dividend refund or was excluded from the suspended dividend rules.
Related terms
As businesses start planning in anticipation of the proposed new rules taking effect, understanding the following terminology is essential:
- Affiliated corporations: Corporations are deemed to be affiliated where they are controlled by persons who are themselves affiliated with one another (including spouses) whether the corporations are controlled by a single person or by affiliated groups of persons.
- Connected corporations: Corporations where the payor is controlled by the recipient together with related or non-arm's length persons—or where the recipient owns more than 10 per cent of the payer's votes and value.
- Eligible dividends: Dividends paid from income that is usually taxed at the higher general corporate tax rate and therefore receives more favourable tax treatment when paid to individuals.
- Non-eligible dividends: Dividends generally paid from income that benefitted from preferential corporate tax rates—such as the small business deduction—and therefore receive less favourable tax treatment when paid to individuals.